Rent-to-Own Property in Kenya: How It Works, Benefits, Risks and What Buyers Should Know
Buying a home is a significant financial commitment, and for many aspiring homeowners in Kenya, raising the required deposit or qualifying for mortgage financing can be challenging. This has created interest in alternative property ownership arrangements, including rent-to-own agreements.
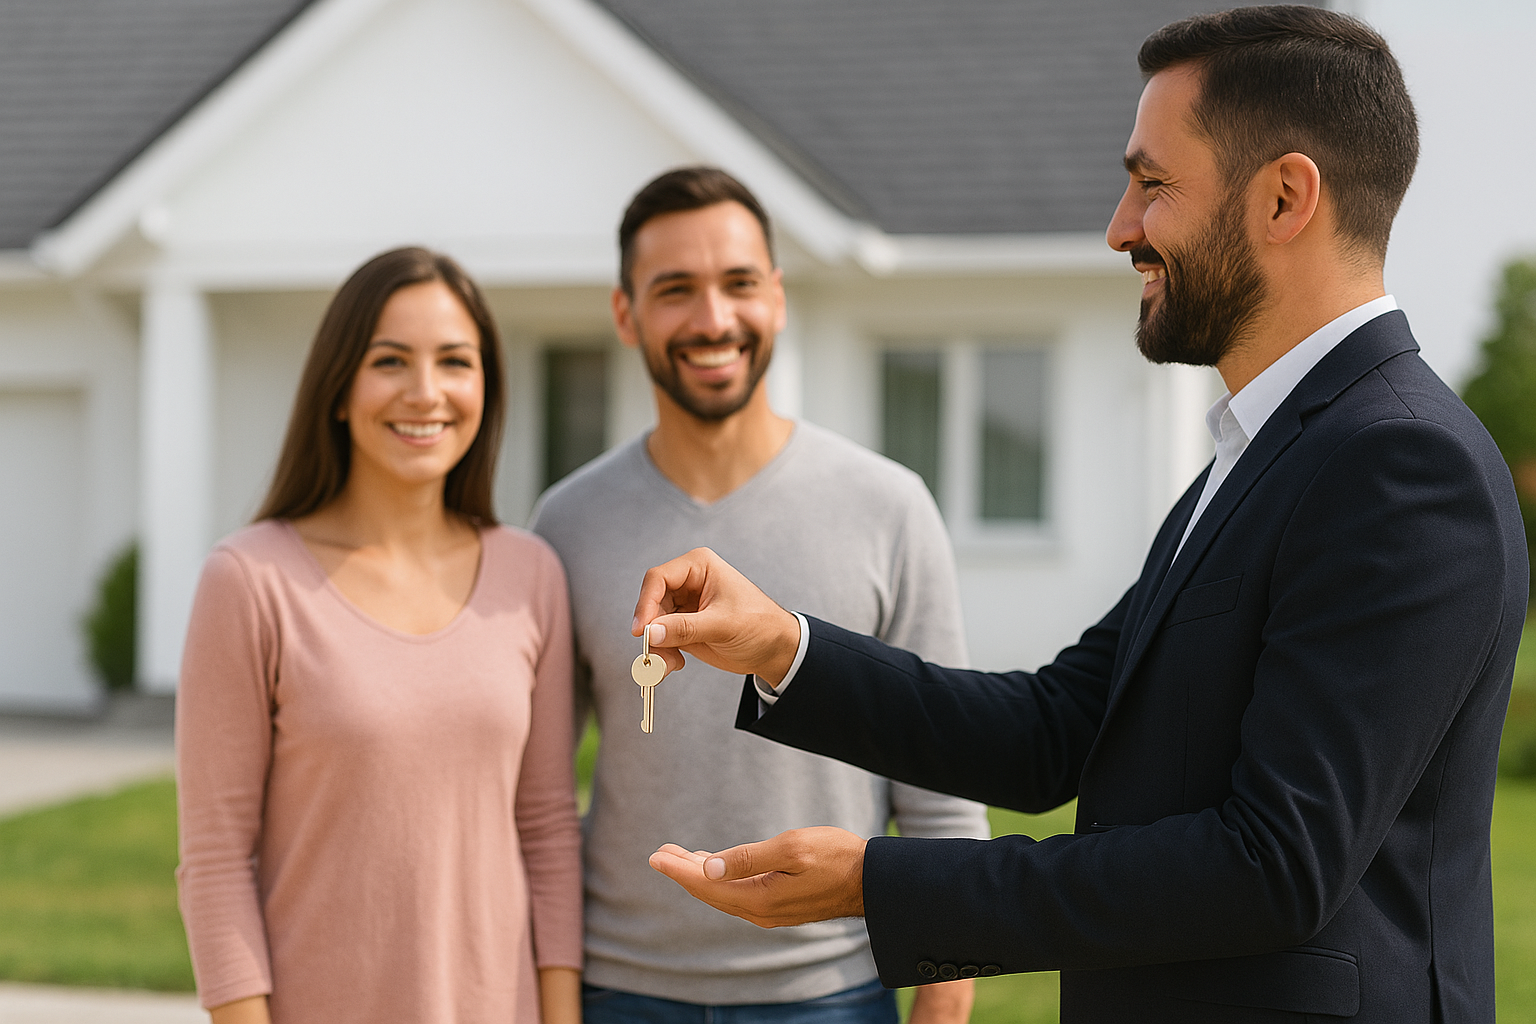
Rent-to-own property is a homeownership arrangement that allows an individual to rent a residential property for an agreed period, with the option to purchase it at a later date under predetermined contractual terms. Depending on the agreement, a portion of the monthly rent may be credited towards the eventual purchase price.
For individuals looking to own apartments, townhouses or other residential properties in Kenya, this arrangement can provide additional time to prepare financially before committing to a property purchase.
How Does Rent-to-Own Work in Kenya?
A rent-to-own property arrangement combines a residential tenancy agreement with an option to purchase the property. Although the specific terms vary between landlords, developers and buyers, the process generally involves the following stages:
1. Property Selection and Agreement
The prospective buyer identifies a suitable property, such as an apartment, townhouse or residential home. Both parties agree on the rental period, proposed purchase price, payment structure and conditions for exercising the purchase option.
2. Initial Option Fee
Some rent-to-own arrangements require an upfront option fee to secure the buyer’s right to purchase the property within an agreed period. Whether this payment is refundable or deducted from the purchase price must be clearly stated in the agreement.
3. Monthly Rental Payments
The buyer occupies the property and makes monthly rental payments. Under certain agreements, a specified portion of the rent is accumulated as a rent credit towards the eventual purchase price.
4. Property Purchase
At the end of the agreed rental period, the buyer may exercise the purchase option by completing the remaining payment obligations. This may involve personal savings, mortgage financing or another agreed payment arrangement.
It is important to understand that rent credits, purchase options and upfront fees are not automatic features of every rental agreement. They must be expressly negotiated and documented.
Benefits of Rent-to-Own Property
Rent-to-own arrangements can offer several advantages to individuals working towards homeownership in Kenya.
1. More Time to Prepare Financially
One of the main advantages is the opportunity to build savings while occupying the intended property. This can help prospective homeowners prepare for the financial requirements associated with purchasing residential real estate.
2. An Alternative Path to Homeownership
For buyers who may not be ready to make an immediate property purchase, rent-to-own can provide an alternative arrangement, subject to the availability of suitable agreements.
3. Opportunity to Experience the Property
Living in a property before purchasing it allows buyers to assess the surrounding neighbourhood, accessibility, security, available amenities and general suitability of the home.
4. Potential Purchase Price Certainty
Where the purchase price is agreed upon and fixed in the contract, buyers may benefit from knowing the anticipated acquisition cost in advance. However, they should also consider the possibility of market prices changing during the rental period.
Risks and Disadvantages of Rent-to-Own Agreements
Although rent-to-own can offer flexibility, prospective buyers should understand the financial and contractual risks involved.
- Non-refundable payments: Some agreements include upfront fees or accumulated payments that may be forfeited if the buyer does not complete the purchase.
- Mortgage financing requirements: A rent-to-own arrangement does not automatically guarantee mortgage approval when the purchase period ends.
- Property market fluctuations: The agreed purchase price could become higher than the property’s prevailing market value.
- Maintenance responsibilities: Depending on the contract, the occupant may be responsible for certain repairs, maintenance costs and property-related expenses.
- Contractual disputes: Unclear payment terms, ownership conditions or termination clauses can create disagreements between the parties.
Before entering into an agreement, buyers should establish their financial obligations and understand what happens if they are unable to complete the purchase.
Who Should Consider Rent-to-Own Property?
Rent-to-own may be worth exploring for different categories of prospective homeowners.
First-Time Homebuyers
Individuals purchasing their first home may benefit from having additional time to organise their finances and prepare for the costs of property ownership.
Self-Employed Professionals and Entrepreneurs
Individuals with irregular income streams may prefer a structured arrangement that gives them time to strengthen their financial position before pursuing a conventional property purchase.
Kenyan Diaspora Buyers
Kenyans living abroad who intend to relocate may explore property arrangements that allow them to secure a potential future home while planning their return.
Individuals Preparing for Mortgage Financing
Prospective buyers who need additional time to accumulate a deposit or improve their eligibility for mortgage financing may also consider this option.
Important Factors to Consider Before Signing a Rent-to-Own Agreement
A rent-to-own agreement involves more than simply paying rent with the intention of purchasing a home. Buyers should conduct proper due diligence before committing.
Consider the following:
- Engage a qualified property lawyer: Have an independent advocate review the agreement, ownership documents and purchase conditions.
- Verify property ownership: Conduct an official land search to establish the registered ownership and identify any encumbrances affecting the property.
- Understand the payment structure: Establish how much of the monthly rent, if any, will be credited towards the purchase price.
- Clarify termination conditions: Understand what happens to your payments if you decide not to purchase or cannot complete the transaction.
- Inspect the property: Assess the property’s structural condition, utilities, security and general suitability before signing.
- Account for additional costs: Consider legal fees, valuation costs, stamp duty, service charges and other applicable property acquisition expenses.
- Confirm the transfer process: Establish when and how legal ownership will be transferred upon completion of the purchase.
A properly structured agreement should clearly define the responsibilities of both parties and protect their respective interests.
Is Rent-to-Own a Viable Homeownership Option in Kenya?
Rent-to-own is an alternative homeownership arrangement that prospective buyers in Kenya can explore, although its availability and contractual structure vary across the property market.
Other property acquisition options include developer payment plans, instalment-based property purchases, tenant-purchase arrangements and conventional mortgage financing.
For buyers considering apartments for sale in Nairobi, townhouses or residential developments in other parts of Kenya, comparing these options can help identify an arrangement that matches their financial circumstances and long-term property ownership goals.
The most suitable option will depend on the purchase price, payment period, financing requirements, legal terms and the buyer’s financial capacity.
Final Thoughts: Making an Informed Property Investment Decision
Rent-to-own can provide an alternative route towards homeownership for individuals who need more time to prepare financially before purchasing a property.
However, the arrangement requires careful financial planning, proper legal documentation and a clear understanding of the purchase conditions.
Whether you are a first-time homebuyer, a property investor or a Kenyan living abroad planning to acquire residential property, understanding the available homeownership options is an important step towards making a sound real estate investment decision.
At Emaar Consults, we recognise the importance of informed property decisions and the value of finding residential spaces that align with individual needs and long-term investment objectives.